This is not investment advice. Margin and options can magnify risk. I am documenting my own historical reasoning.
Why I Bought Amazon Before the Stock Split
On 17 March 2022, I assisted in buying one AMZN share for my fiancée at $3,101.99. Amazon had generated more than $100K for me through Amazon Associates, and much of my stock-market capital came from that work. That made owning the stock feel personally important to me.
The goal was to hold five shares by 6 June 2022, before the planned split, and to keep the stock for at least one year.
The Covered-Call Plan
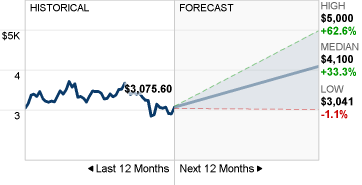
The plan was prospective: after a 20-for-1 split, five pre-split shares would become 100 shares, enough for one standard covered-call contract. I wrote that if the average purchase price was close to or above the stock price, I was looking at roughly $150 weekly or $500 monthly from covered calls. Those were historical expectations, not a documented premium, strike, expiry, completed call sale, or realized result.
Why Margin Was Part of the Setup
Five shares at roughly the then-current pre-split price would have required about $15,000, which we did not have in cash. My stated idea was to use Interactive Brokers margin at about 6.66x: invest about $2,250 while carrying a negative cash balance of around $13,000.
That margin decision was separate from the covered-call plan. It increased the stock exposure and made a price decline more consequential; it could also involve financing costs and margin pressure. A covered call does not remove those risks.
What the Stock Split Changed
On 9 March 2022, Amazon’s board approved a proposed 20-for-1 split subject to shareholder approval. The article recorded the then-expected timetable: shareholder record date 27 May, shares reflected around 3 June, and split-adjusted trading expected 6 June. The split would change the share count and per-share price proportionately; it would not itself create investment value.
What Could Go Wrong
- AMZN could decline while the margin exposure amplified the downside.
- Financing costs and margin requirements could affect the position independently of option premium.
- A covered call would cap upside above its strike while leaving substantial stock downside.
- Timing a plan around a split did not guarantee an attractive option premium or a stable share price.
What Happened
The original article does not record whether the remaining four shares were bought, whether a covered call was sold, the final margin balance, or the investment outcome. This remains a pre-split plan and leverage case study rather than a completed trade report.
What I Learned
Looking back, the key distinction is between owning a covered underlying and financing it with leverage. Covered calls can modestly change an income profile, but they do not make a leveraged stock position low risk. The margin exposure, event timing and stock downside needed their own analysis.
How This Differs From My SOL Covered Calls
This historical AMZN plan combined an equity event and margin. My SOL covered-call guide explains a separate, fully funded crypto-underlying framework and its own risks. Neither is a substitute for considering the underlying exposure first.
Related Trading Strategies
See Trading Strategies for the broader cluster. My cash-secured-put stock-selection framework covers another ownership-oriented options approach.