I've been selling cryptocurrency options for several years, primarily focusing on Bitcoin and Ethereum. In September 2025, I decided to expand my options-selling activities to Solana, combining long-term SOL accumulation with selective covered calls and cash-secured puts.
A year is long enough to move past the first impression of a new market. I can now ask a more useful question than whether SOL options exist: after one year of trading them, has the market matured enough to support systematic covered-call and put-selling strategies as reliably as Bitcoin or Ethereum?
My answer is cautious. SOL options are more accessible than when I began. There are several credible venues, weekly contracts exist, and a regulated CME product has arrived. Yet access is not the same as liquidity, and liquidity is not the same as rollability. What looks attractive on the option chain can become much less attractive when the position needs to be changed.
In my experience, the problem is not necessarily opening the trade. The problem appears when it needs to be managed: a call is challenged, I want a higher strike and a nearer expiry, and the contract that is technically listed is not a useful execution.
That doesn't make SOL options unusable. It does mean the strategy has to start with a much more serious willingness to accept assignment than the same trade might require in BTC or ETH.
What Changed Since I Started Trading SOL Options in September 2025
The SOL options market is broader today than when I started running my Solana options strategy in September 2025. Deribit and Bybit both offer SOL options, CME added options on standard and Micro SOL futures in October 2025, and additional venues such as Derive and Binance now contribute to the market.
There are also more expiries available than I initially assumed. Weekly SOL options do exist, alongside monthly and longer-dated contracts. On paper, that gives traders more flexibility.
In practice, however, having an expiry listed does not necessarily mean there is a useful trade available.
That distinction has become increasingly important in my own strategy. When a covered call moves against me, I'm not simply looking for another expiry. I need a strike further out, at a sensible premium, with enough liquidity to close the existing position and open the new one without giving up too much in the spread.
This is where SOL still feels very different from BTC or ETH.
The market has grown, but my experience over the past year suggests that usable liquidity can still disappear quickly once we move away from the most active strikes and expiries. A weekly contract may exist, but the roll I actually want may offer little or no credit, have a wide spread, or force me much further out in time than I would prefer.
That is the real issue: not whether SOL options exist, but whether they provide enough flexibility once a position needs to be managed.
Where SOL Options Trade Today
My September 2026 venue review found four active offshore venues in Loris Tools' cross-exchange SOL dashboard: Deribit, Bybit, Derive and Binance.
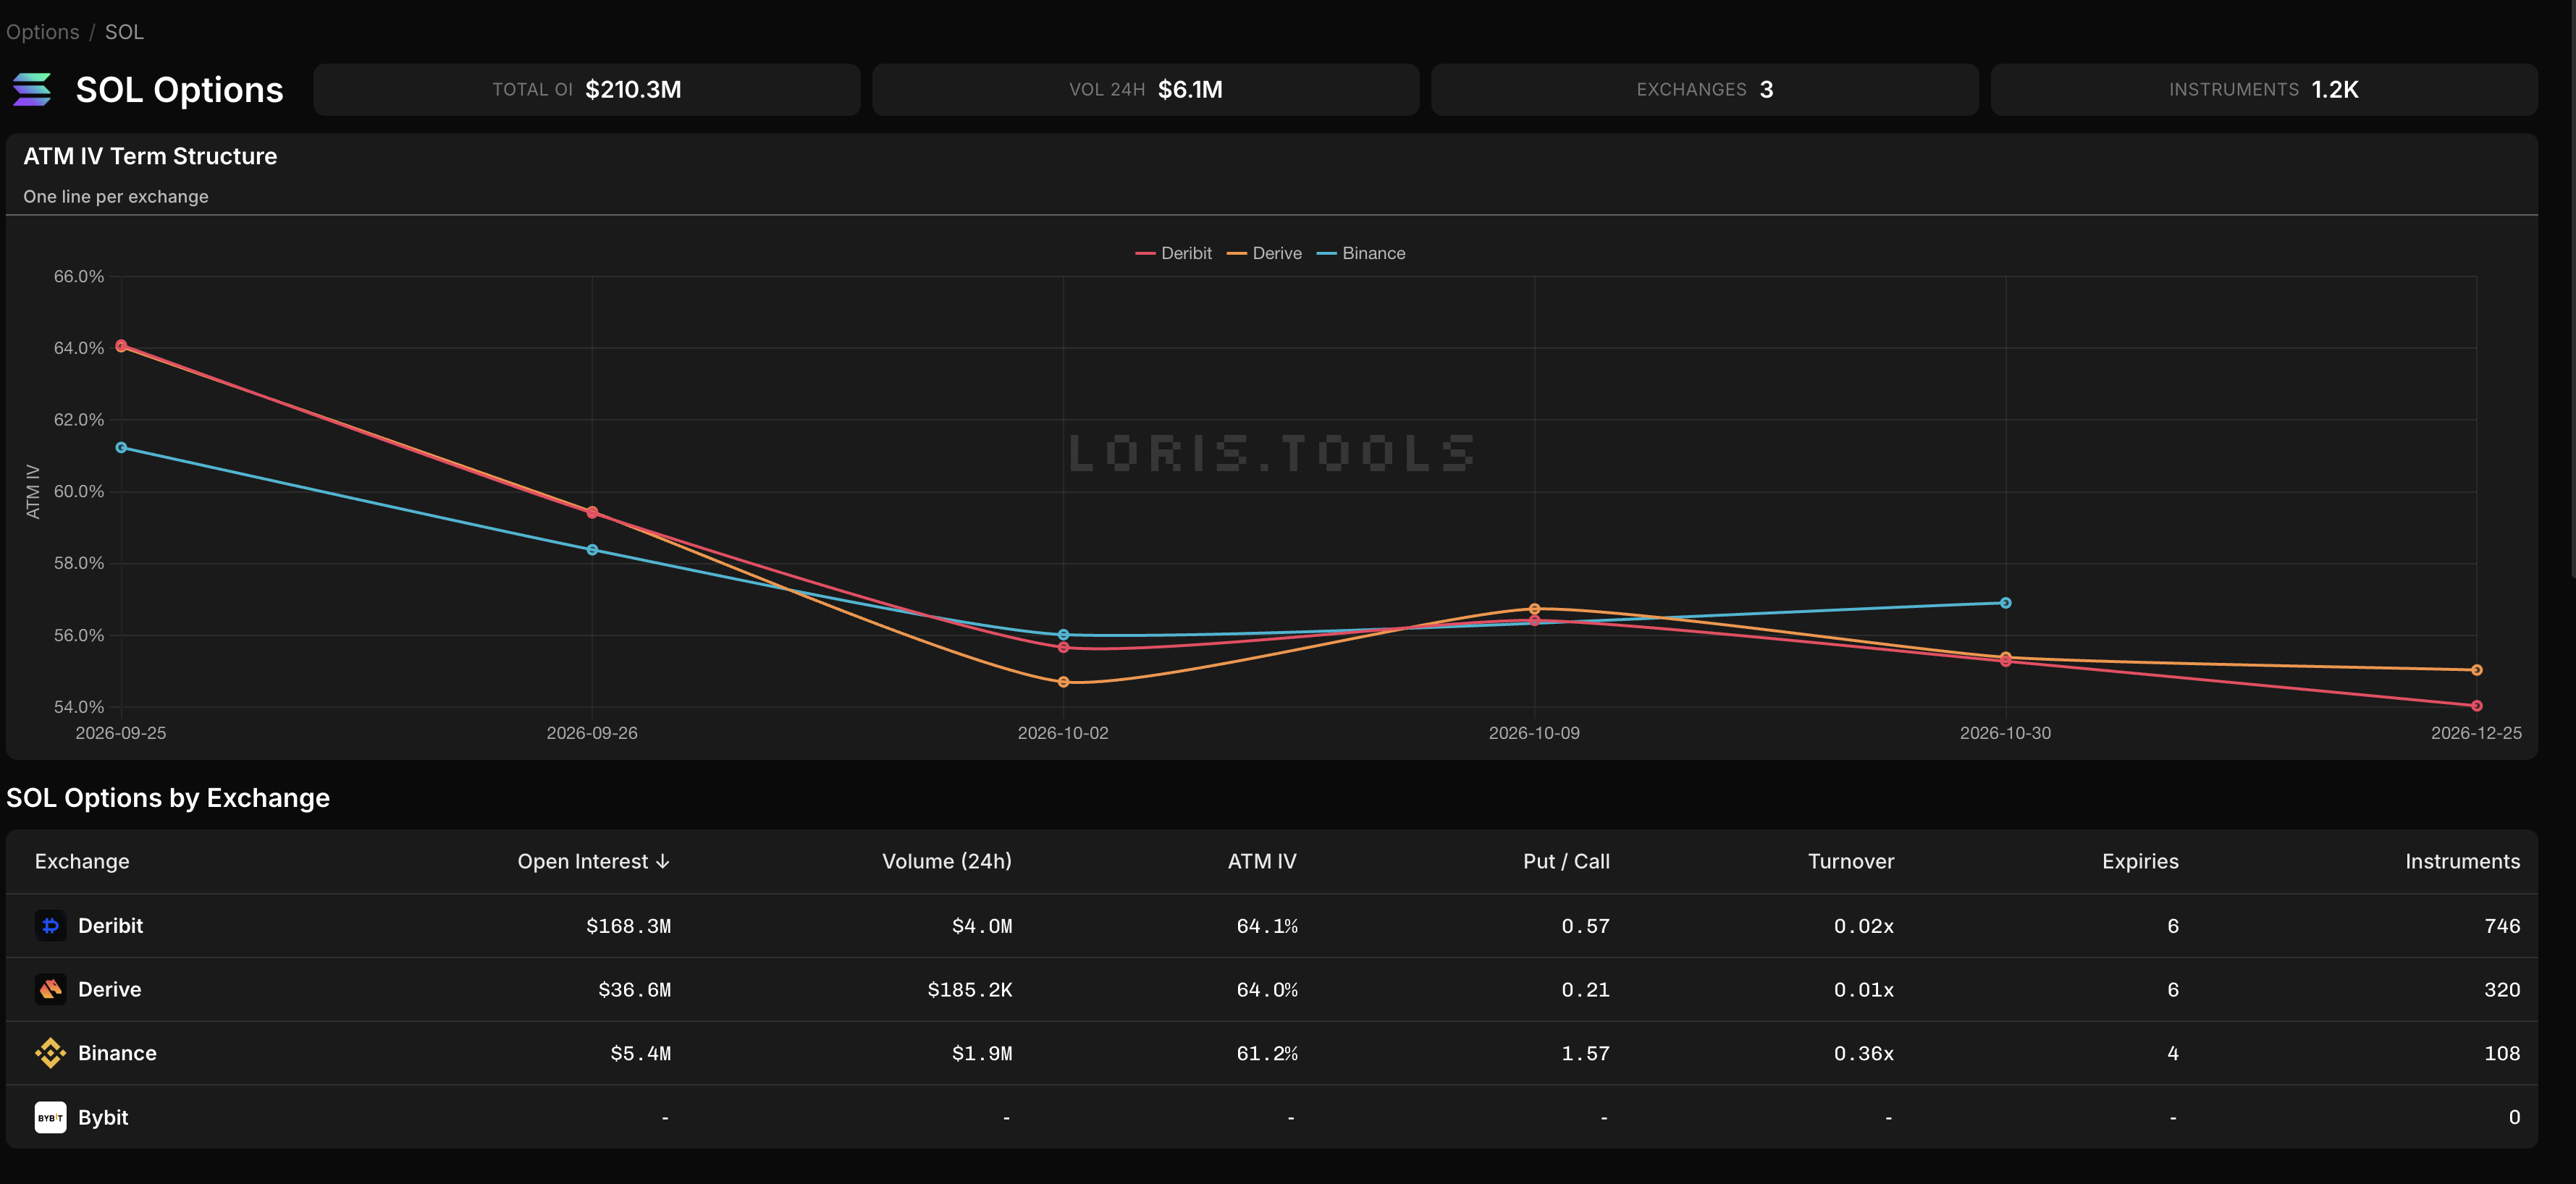
The dashboard reported $227.35 million of tracked SOL open interest, $14.04 million of 24-hour notional volume and 1,564 active instruments across those venues at the time checked.
Deribit dominated: $167.65 million of open interest, $3.94 million of 24-hour volume, six expiry groups and 744 listed instruments. Derive reported $36.47 million of open interest; Binance $5.33 million.
Bybit's venue page reported 158,127 aggregate SOL option contracts open and 71,181 contracts of 24-hour volume, but contract counts are not directly comparable with dollar notional across exchanges.
There is also a distinct regulated market. CME's SOL and Micro SOL options are options on futures, not spot-covered calls. That matters for collateral, settlement and the position being hedged.
CME's launch notice says that daily, monthly and quarterly expiries are available; its 2026 rules show Monday through Friday weekly series and progressively denser strikes nearer expiry. Those products expand institutional access, but their existence should not be treated as proof that a spot holder can roll an offshore covered call efficiently.
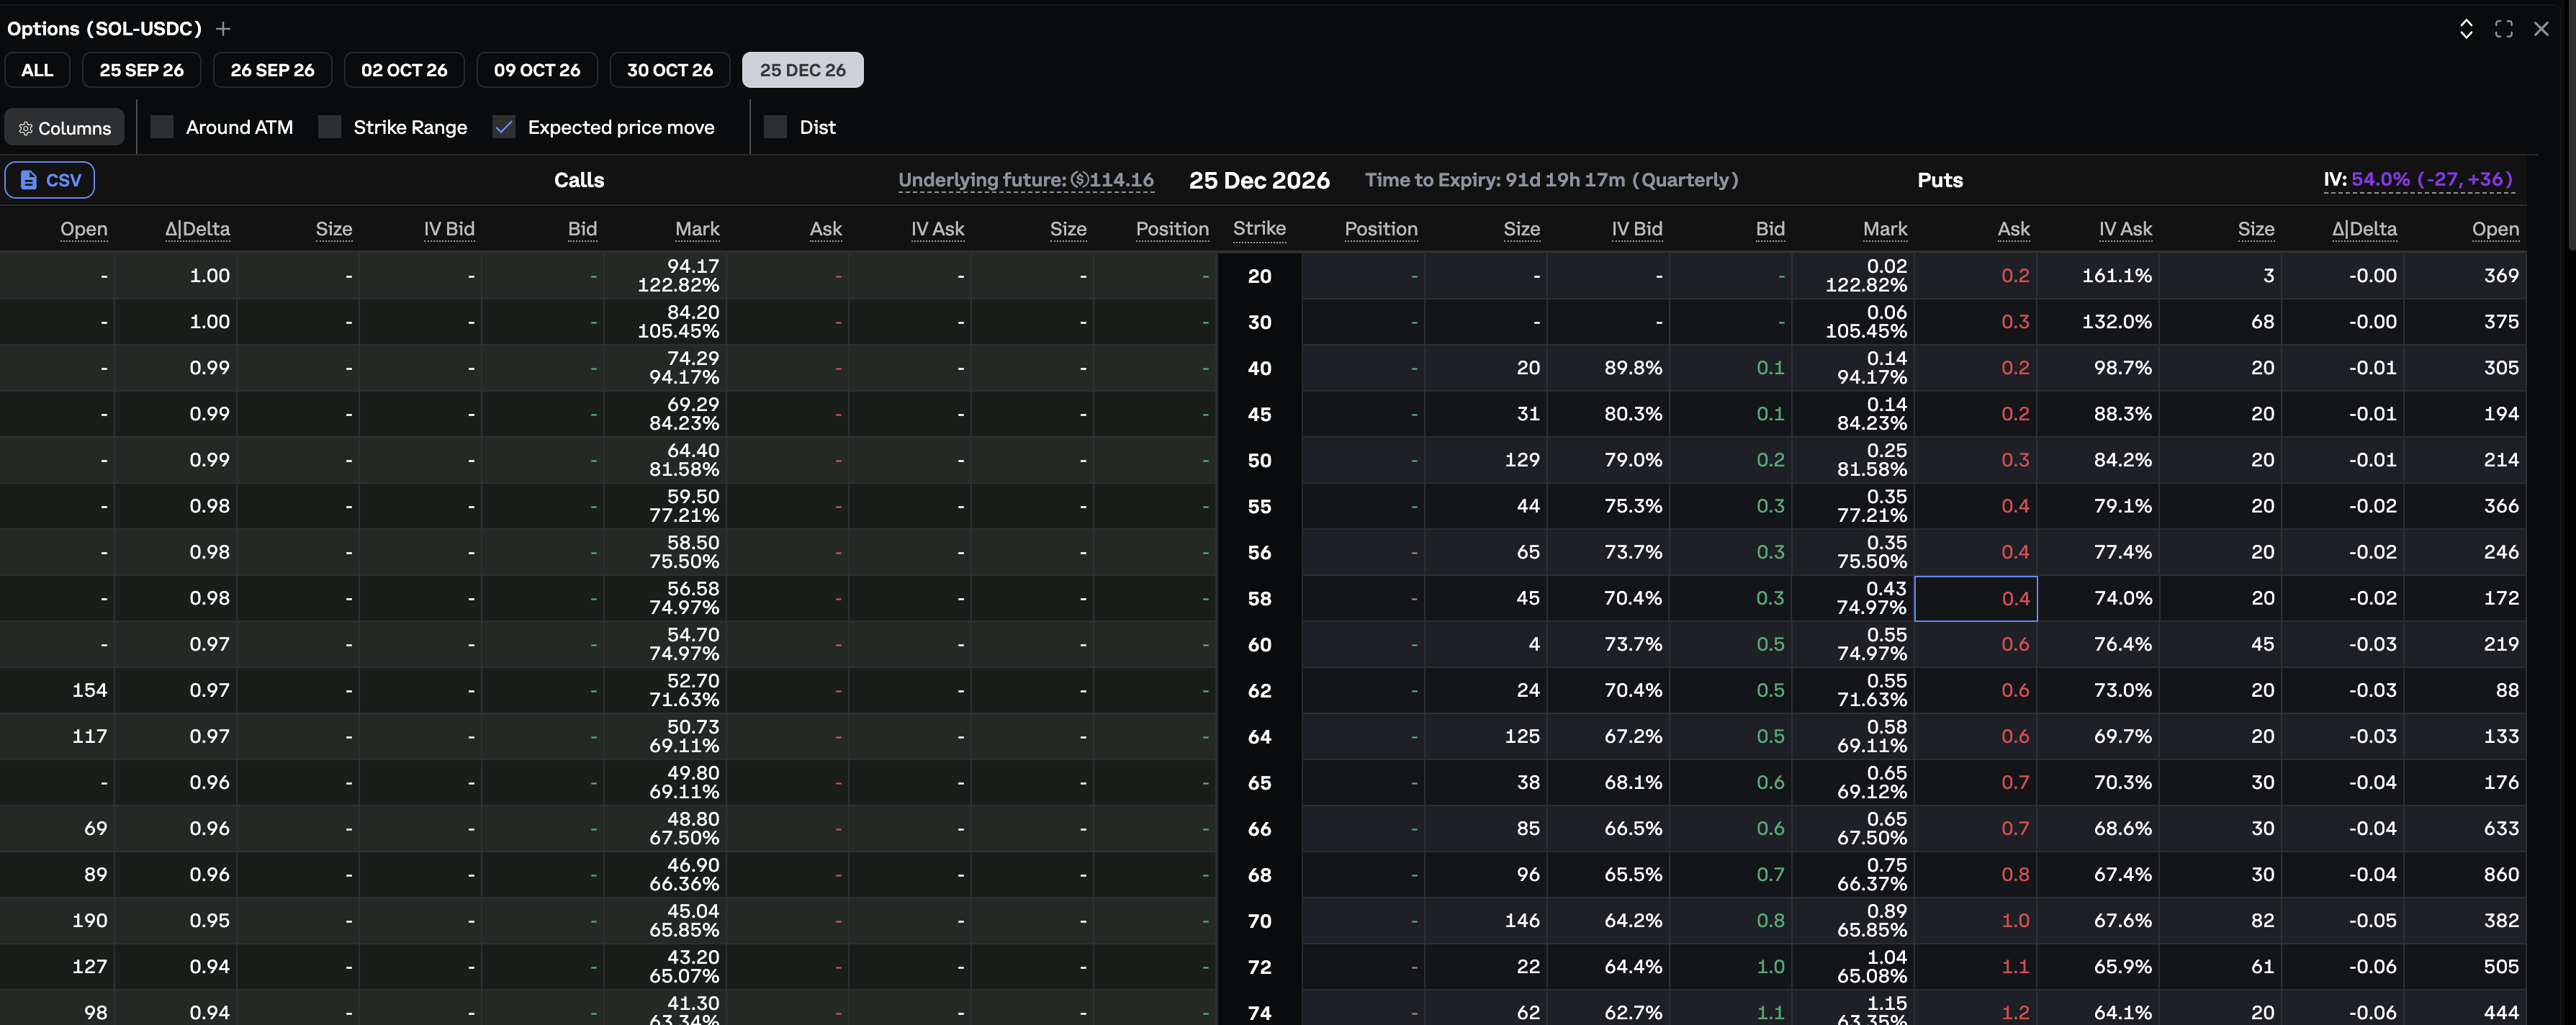
Deribit is the clearest public window into chain construction. Its USDC summary showed six SOL expiry dates and 744 SOL instruments in my September snapshot. Half displayed both a positive bid and ask.
That is a useful warning rather than a universal spread statistic: a two-sided quote does not tell us how much size is available, whether it survives an order, or whether it sits near a fair midpoint.
It does show why counting listed contracts can overstate usable choice.
Availability, Liquidity and Rollability Are Different Things
"Liquidity" is too broad to guide a real trade. I separate it into five tests.
- Entry liquidity. Can I open the call or put I actually want at a reasonable bid/ask spread and meaningful size?
- Exit liquidity. Can I later close it without surrendering much of the premium collected at entry?
- Rolling liquidity. Can I close a challenged option and open a useful replacement—higher or lower strike, appropriate expiry—without turning the adjustment into a poor trade?
- Expiry liquidity. A Friday contract is not automatically useful merely because it is listed. Its relevant strikes still need tradable quotes.
- Strike liquidity. The market may quote near ATM while a covered-call seller needs a materially OTM strike. Liquidity often deteriorates precisely where the strategy needs it.
Open interest is only one of those tests. A contract can have open interest from an earlier transaction and still offer no compelling bid when I need to leave. A screen can show a bid and ask while the spread consumes most of a small premium.
A quoted weekly can be irrelevant if moving a Friday call one week forward and $5–$10 higher produces negligible credit or a worse risk/reward profile.
This is the practical expiry problem behind many of my decisions. I may prefer to move a challenged call from one Friday to the next. If the useful strike has no real bid, the spread is too wide, or the credit is too small, the next acceptable choice can be an end-of-month contract 30–45 days out.
That ties up the covered SOL for longer, reduces opportunities to re-select the strike, makes annualized premium less meaningful, and leaves upside capped through a larger part of a volatile move.
What a Year of Real SOL Trades Taught Me
When I started selling Solana options in September 2025, my objective was relatively simple: accumulate SOL over time, selectively sell covered calls and cash-secured puts, and reinvest the premium where practical.
The idea wasn't particularly different from what I've been doing with Ethereum and Bitcoin, although the market structure turned out to be quite different.
Early on, the objective was to compound a spot position rather than distribute an income stream. My September 4, 2025 launch journal recorded an explicit focus on steadily growing the underlying SOL position.
The original expectation was that a growing derivatives ecosystem would make the overlay progressively easier to manage. A year later, that expectation needs qualification.
In Episode 126 of my trading journal, I recorded that my SOL calls had reached a point where suitable roll dates were limited.
In Episode 143, my response was to keep calls limited because the position was well below its break-even and the premium available did not justify surrendering much recovery potential.
That wasn't a prediction about SOL. It was portfolio triage: when I want to rebuild spot exposure, cheap upside caps are counterproductive.
The problem became more concrete in Episode 158.
SOL had rallied from roughly $89 to $108, while my calls were challenged. I closed 16 SOL $84 calls because there were no suitable contracts available to roll up and forward.
Rather than maintain the cap, I sold 16 $83 puts expiring at month-end.
That exchanged capped spot upside for additional downside and assignment exposure. It wasn't a free improvement; it was the least objectionable available adjustment.
Episode 159 documented roll-forwards from end-September to end-October. The rolls collected time premium and could improve the structure, but they also extended the period in which upside was capped.
The following week, Episode 160 rolled five $90 SOL calls to October 30 at a higher $95 strike.
The higher strike required a small debit; five additional $120 calls were sold to make the combined adjustment a modest net credit.
The mechanics worked, but they illustrate the compromise: a better strike wasn't simply available for free, and the solution extended the exposure.
My September 2026 journal makes the assignment lesson unavoidable.
Fifteen SOL were allowed to go at predefined $85 and $90 strikes after calls expired with SOL above them.
I didn't regard the original trades as automatically wrong. I concluded that the chain didn't offer a roll I considered attractive enough to preserve the underlying.
My position fell below 60 SOL, while my stated long-term target remained at least 100 spot SOL.
I chose to rebuild gradually rather than force a poor adjustment.
The Covered-Call Problem: Real Premium, Surrendered Upside
A covered call is not a yield product that happens to hold SOL. It is a sale of upside above a chosen strike.
The distinction is especially important for an asset that can move sharply.
Take a simple illustration.
An investor owns SOL at $80 and sells a $90 call.
If SOL drifts toward $90, the premium may be useful and the planned exit can be reasonable.
If SOL jumps to $120, however, a small premium looks insignificant beside the $30 of appreciation above the strike that the seller has surrendered.
The trade may still have followed its stated rules; it has simply exchanged a large upside outcome for a much smaller premium receipt.
In a deeper market, the seller may be able to buy back the old call and sell a higher, later one at a tolerable debit or credit.
That is not a guarantee in BTC or ETH, but their larger chains normally provide more candidate strikes and dates.
With SOL, thinner OTM and roll liquidity can leave three unattractive choices: accept assignment, buy back an expensive call, or extend much further out than intended.
I discovered this the hard way.
The operating rule that follows is simple: selling a SOL covered call should mean being genuinely comfortable selling the SOL at that strike.
Relying on the assumption that it can always be rolled later is dangerous.
SOL Options Versus BTC and ETH
To put the liquidity problem into perspective, here is how the three options markets compared in my September 2026 snapshot.
| Practical dimension | SOL | BTC | ETH |
|---|---|---|---|
| Tracked open interest | $227m | $41.26bn | $6.68bn |
| 24-hour volume | $14m | $2.92bn | $1.27bn |
| Tracked venues | 4 | 5 | 5 |
| Expiry and strike choice | Weeklies exist, but useful choice can cluster | Deeper and more flexible | Deeper and more flexible |
| OTM quotes and size | Less reliable away from the centre | Generally broader | Generally broader |
| Entry and exit | Must be checked contract by contract | More robust across the chain | More robust across the chain |
| Rolling challenged calls | Often the limiting decision | Usually more alternatives | Usually more alternatives |
| Best fit | Selective, assignment-ready trades | More suitable for systematic cycles | More suitable for systematic cycles |
The gap isn't marginal.
The same Loris snapshot placed SOL open interest at roughly 0.55% of BTC's and 3.4% of ETH's.
It recorded 1,564 active SOL instruments versus 3,656 BTC and 3,410 ETH.
Those figures don't measure every order book, but they support the broad conclusion from my trades: the underlying can be attractive while the options market remains less attractive for a roll-dependent strategy.
For context, I also actively trade Ethereum and Bitcoin options as part of my broader crypto strategies, some of which contribute to the trading and treasury activities associated with TerraM Token.
The comparison matters because a strategy that works relatively smoothly on Bitcoin or Ethereum cannot simply be copied to Solana without adjusting expectations around liquidity, execution and assignment risk.
Reasons I Still Want to Own SOL
Despite these challenges, I remain interested in accumulating Solana.
There are several reasons.
Network activity is real, even if it is uneven. Solana has a broad application and trading ecosystem. In the September 2026 DefiLlama chain view, DEX volume, fees, stablecoin activity and a large protocol set were visible alongside more speculative activity.
I don't treat any one metric as a valuation model. I do see a network with actual economic use and infrastructure worth monitoring.
It is high-beta exposure to crypto adoption. SOL has historically reacted strongly in risk-on periods. That creates meaningful upside potential if the ecosystem and broader crypto market develop well.
It also creates a sizing problem: the same beta that attracts holders can make a small covered-call premium a poor exchange for a large move.
There are several potential sources of utility. Staking, DeFi, payments, trading infrastructure and selective option premium can all be relevant.
None is a free return. Staking has validator and protocol risk; DeFi introduces smart-contract, liquidity and counterparty risk; option premium is compensation for real downside, upside and execution risk.
Solana is also the blockchain on which TerraM Token operates, giving me another reason to follow developments in its ecosystem closely. That connection doesn't change my investment analysis of SOL, but it adds practical interest in network liquidity, decentralized exchanges and market infrastructure.
Reasons an Investor May Reasonably Decide Not to Own SOL
There are also good reasons to remain cautious.
Volatility can overwhelm the strategy. A covered call doesn't protect a holder when SOL falls sharply. My own record includes long stretches in which the position remained below its cost basis despite premium collection.
Position sizing matters more than annualized yield calculations.
Competition and technology remain unresolved. Ethereum, Ethereum L2s and other high-throughput networks compete for users, liquidity, developers and applications.
Solana also carries execution, infrastructure-concentration and operational risks. Network activity today isn't a guarantee of durable dominance.
Token valuation can diverge from use. SOL can reprice on risk appetite, liquidity, narratives and speculative trading, including memecoin cycles.
Genuine network use doesn't tell us that the token is cheap, nor does it prevent a long period of weak price performance.
When SOL Puts and Calls Make Sense—and When They Do Not
Selling a cash-secured SOL put can make sense when I genuinely want to acquire SOL at the strike, collateral is available, the premium survives a realistic spread and I can hold through assignment.
It's less sensible when the trade is merely a search for annualized yield or when an assignment would create an oversized position.
A SOL covered call can make sense when the selected strike is an honest planned sale price, the expiry and execution are acceptable, the position is small enough, and I don't require frequent rescue rolls.
It becomes much more problematic when the plan depends on precise delta selection, narrow spreads, weekly recycling, short-duration alternatives or actively defending a call while refusing to sell the SOL.
For my own portfolio, the central conflict is clear.
The stronger my conviction in owning and accumulating SOL, the weaker the case becomes for aggressively selling calls against it.
My long-term objective is to build a position of at least 100 spot SOL. Repeatedly capping an asset I want to keep can directly undermine that objective.
Premium available today is not a sufficient reason to take that trade.
What I'm Changing After One Year
I remain interested in SOL and will probably continue to use options selectively.
But I'm no longer treating the strategy as an automatic weekly income machine.
I'll put more weight on strike selection, liquidity at the actual roll candidates, position size and a genuine willingness to accept assignment.
When the chain doesn't support those conditions, doing nothing is a valid decision.
The year changed my view without producing a simplistic verdict. SOL options have developed: access, venue count and listed contracts are better than the market I entered.
What improved less dramatically in my own execution was the ability to move an existing position into the exact strike and expiry I wanted at an acceptable price.
For BTC and ETH, the market often gives me several ways out. For SOL, that flexibility is still less reliable.
That is why my default is becoming more conservative.
The premium is real. So is the upside I surrender.
If I sell a SOL call, I should be prepared to deliver the SOL at its strike—not assume that a future roll will save a decision I wouldn't otherwise accept.
Disclaimer: This article documents my personal trading experience as of September 24, 2026. It is not investment advice. Cryptocurrency options involve substantial market, liquidity, execution and assignment risks.